Escrow Explained: What Happens Between Contract and Closing
Morrell Property Collective September 24, 2026
Buyers
Morrell Property Collective September 24, 2026
Buyers
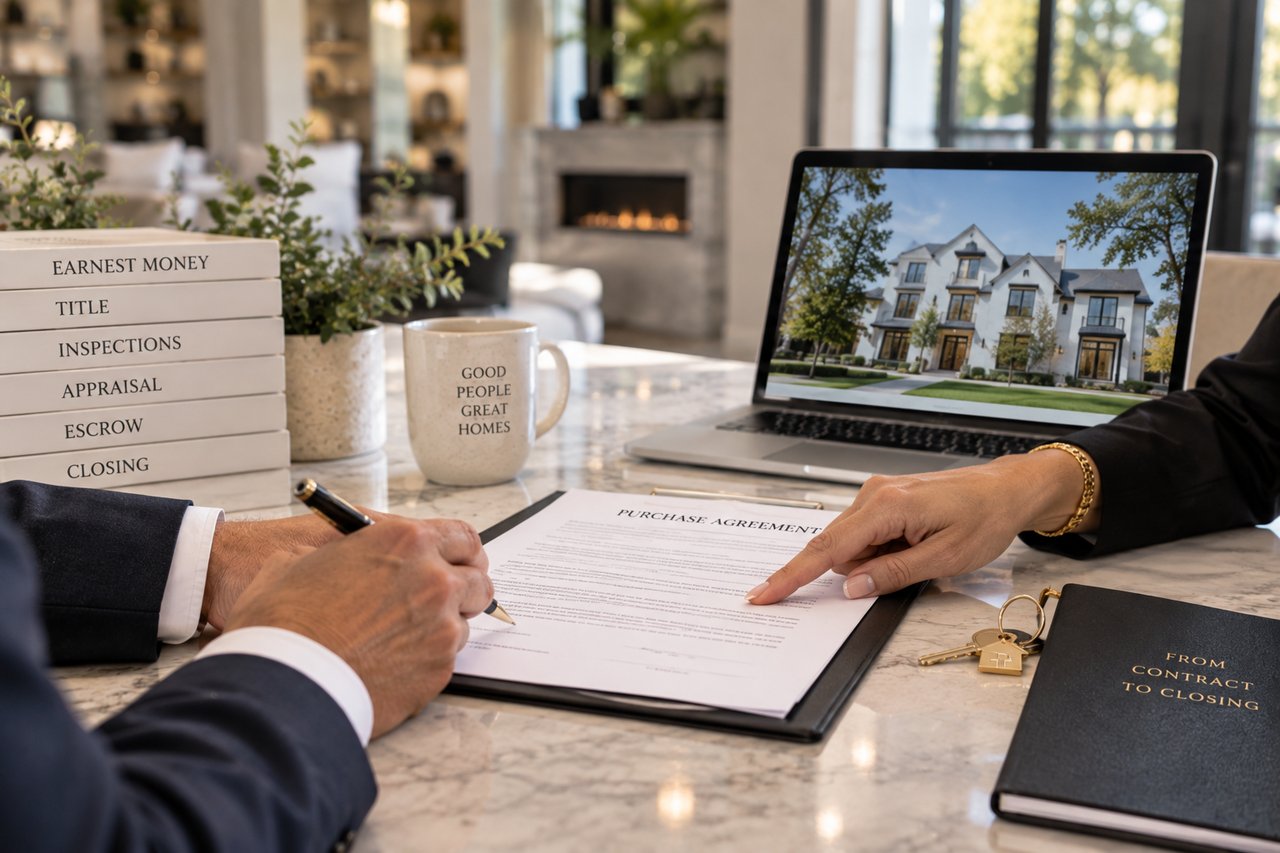
Once a Tennessee purchase agreement is signed, it can feel like the deal is done — but signing is really just the starting gun. What follows is typically 30 to 45 days of earnest money deposits, title work, inspections, an appraisal, and loan underwriting, all leading up to closing day. For buyers and sellers who haven't been through it recently, it helps to know what's actually happening during that stretch, and why.
This post walks through the process step by step, using how it typically works here in Tennessee — where closings run through title companies rather than requiring an attorney at the table, though either side can involve one.
Key takeaways
The contract becomes binding once the last party signs and that acceptance is communicated — from that point, every deadline in the contract is running. Most Middle Tennessee contracts use Tennessee REALTORS® forms, which count deadlines in days from the binding agreement date, so calendaring them right away matters.
Earnest money is usually deposited within a few days of binding agreement and held in a broker's or title company's escrow account — this is the "escrow" most buyers are referring to when they ask what happens during this period. It isn't a separate fee; it's credited back to the buyer at closing. What happens to it if the deal falls through depends entirely on the contract's contingency language, which is one more reason to read those terms closely with your agent.
The title company searches county property records and issues a title commitment — what it will insure, what has to be resolved before closing (existing loan payoffs, releases, corrective deeds), and what it excludes from coverage. Read the exceptions section carefully: easements or restrictive covenants listed there still apply to the property after you own it.
Within the inspection window — commonly 7 to 14 days — the buyer has the property inspected and can accept it as-is, terminate, or negotiate repairs or credits. Tennessee law also requires most residential sellers to provide a property condition disclosure unless the sale is exempt or the buyer waives it.
If the purchase is financed, the lender orders an appraisal to confirm the home supports the loan amount. An appraisal that comes in below the contract price typically triggers a renegotiation — a price adjustment, additional cash from the buyer, or some combination, depending on the contract's appraisal terms.
From there, underwriting verifies income, assets, insurance, and title before issuing final loan approval, often called "clear to close." One practical note for buyers: avoid financing new furniture, opening credit cards, changing jobs, or moving large unexplained sums between approval and closing, since any of those can affect final loan approval.
For financed purchases, federal law requires buyers to receive their Closing Disclosure at least three business days before signing. It's worth comparing that document against the original Loan Estimate and the contract to catch any missing credit or unexpected fee increase before closing day arrives.
The final walkthrough typically happens the day before or morning of closing, to confirm any agreed-upon repairs were completed and the home is in the condition promised in the contract.
Buyer and seller often sign separately at the title company. Funds move under Tennessee's good-funds rules, and wire fraud is a real risk here — always confirm wire instructions by calling the title company at a number you already have, never one from an email. Once the lender funds the loan, the closer pays off the seller's existing mortgage, agent commissions, and prorated taxes, then disburses the seller's proceeds. The deed is recorded with the county Register of Deeds — Davidson County, for Nashville closings — with the buyer customarily paying Tennessee's transfer tax of $0.37 per $100 of the purchase price. Recording is what makes ownership official.
What does escrow mean in a Tennessee home purchase?
Escrow refers to the account — held by a broker or title company — where the buyer's earnest money sits after the contract is signed, until it's credited to the buyer at closing or handled according to the contract's terms if the deal doesn't close.
How long does it take to close on a house in Tennessee?
A typical financed purchase takes about 30 to 45 days from binding agreement to closing; an all-cash purchase can close in as little as a week or two.
Is Tennessee an attorney-closing state?
No. Tennessee closings typically run through title companies rather than requiring an attorney, though either party is free to involve one, particularly if a dispute or unusual issue comes up.
What happens if the appraisal comes in low?
The contract's appraisal contingency governs what happens next — commonly a renegotiated price, the buyer covering the gap in cash, or some split between the two, worked out between the parties.
Who pays Tennessee's real estate transfer tax?
The buyer customarily pays it, at a rate of $0.37 per $100 of the purchase price, due when the deed is recorded with the county Register of Deeds.
Why work with a specialist through this process?
An experienced agent tracks every contract deadline, coordinates with the title company and lender, and flags problems — a low appraisal, a title exception, a financing snag — early enough to resolve them before they threaten the closing date.
The weeks between a signed contract and closing day involve real deadlines and real risk of a deal wobbling — a low appraisal, a title issue, a financing hiccup — but most Tennessee closings go smoothly when those steps are tracked carefully. This isn't legal advice, and a title company or real estate attorney can address anything specific to your contract or situation.
If you're heading into a purchase or sale in Nashville or Knoxville and want a team that tracks these deadlines closely, Morrell Property Collective can walk you through what to expect. Call our team at (615) 593-3103.
Buyers
A step-by-step look at the weeks between a signed Tennessee contract and closing day
Featured Listing
Two mirror-image luxury homes steps from Vanderbilt, Centennial Park, and West End's best dining
MPC Expertise
The licensed brokers, operations, and marketing team behind every transaction
Neighborhood
Where home values concentrate across Music City, from Green Hills to Berry Hill
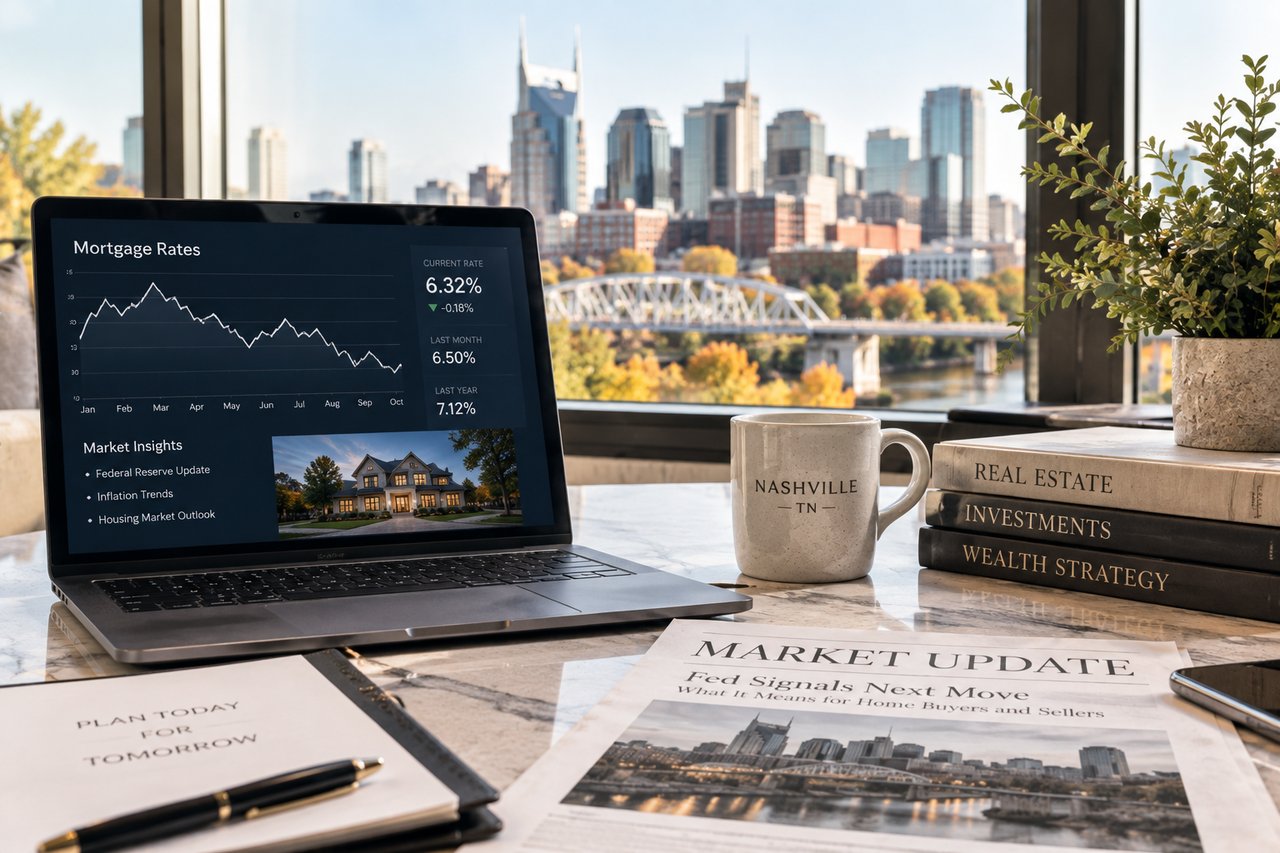
Real Estate Market
What the September rate increase and today's mortgage rates mean for luxury buyers
Neighborhood
Where the season actually shows up in Middle Tennessee
Featured Listing
A room-by-room look at life above downtown Nashville
Real Estate Market
Concierge service, skyline views, and two decades as a downtown fixture
Featured Listing
Low-maintenance, amenity-rich living just south of downtown
The client deserves the full service and attention that only a team of experts can consistently provide. Working with us, you will have the personal attention traditionally associated with the client-agent relationship improved by the professionalism and consistency of a thoughtful business model. And yes, superior results will follow!
MORRELL PROPERTY COLLECTIVE
(615) 593-3103
[email protected]
ADDRESS
3990 Hillsboro Pike, #320
Nashville, TN 37215