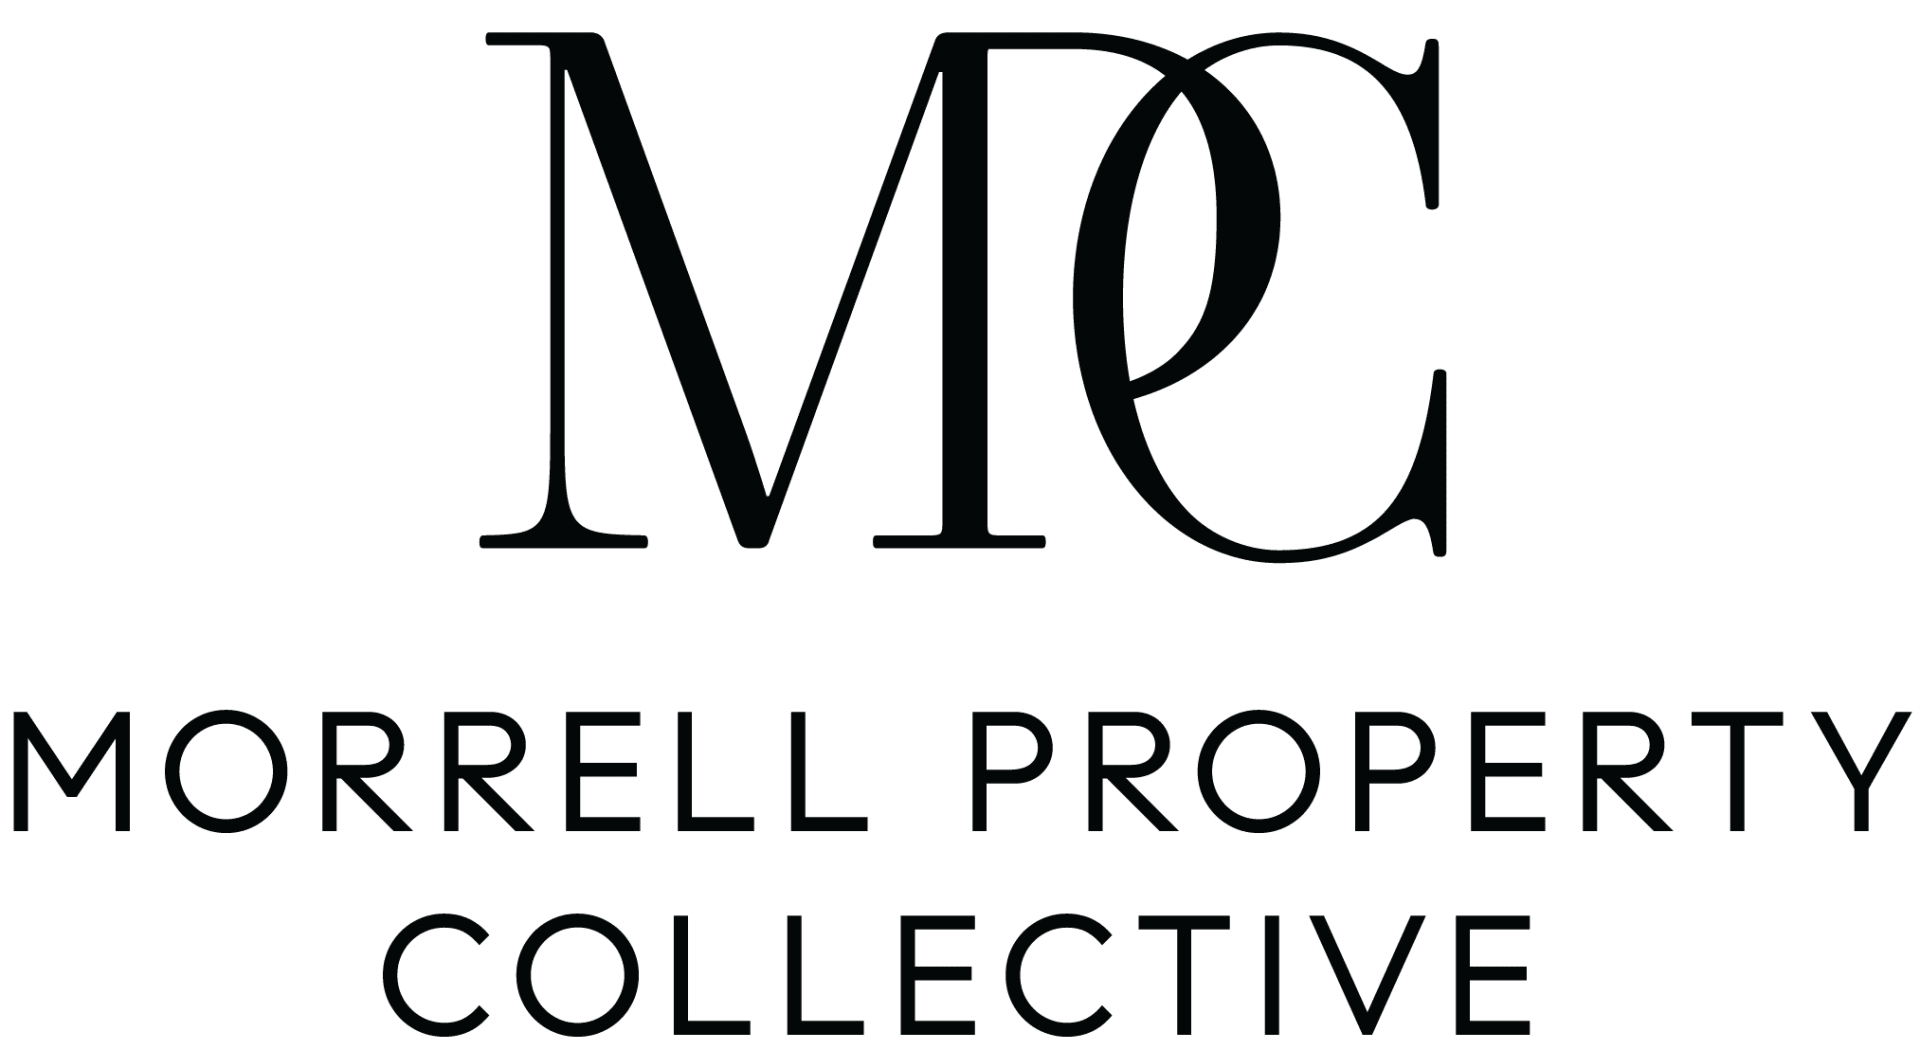Nashville Rate Watch: The Fed's Fall 2026 Move, Explained
Morrell Property Collective September 21, 2026
Real Estate Market
Morrell Property Collective September 21, 2026
Real Estate Market
On September 16, 2026, the Federal Reserve's Open Market Committee raised the federal funds rate target range by a quarter point, to 3.75%–4.00%, in a unanimous 12-0 vote aimed at supporting a return to the Fed's 2% inflation goal. It's the kind of headline that ripples into every corner of the housing market within days — mortgage rates moved before the ink was even dry.
For Nashville's luxury buyers, a rate move like this raises the same question every time: does this change the calculus on buying now versus waiting? This piece walks through what actually happened, what current rates look like, and how to think about financing a luxury purchase in this environment — without pretending to predict where rates go next.
Key takeaways
The FOMC's September 16 decision raised the federal funds rate a quarter percentage point, to a target range of 3.75% to 4.00%, following meetings in January, March, April, June, and July of 2026. The Committee described the move as supporting "a timelier return" to its 2% inflation target. The federal funds rate doesn't set mortgage rates directly, but it influences the broader cost of borrowing that mortgage rates track over time.
Freddie Mac's Primary Mortgage Market Survey put the average 30-year fixed mortgage rate at 6.95% as of September 17, 2026, up from 6.76% the week before and 6.26% a year earlier. The 15-year fixed rate was 6.26%, up from 6.09% the prior week and 5.41% a year ago. Rates are quoted weekly and can shift before a reader sees this, so it's worth checking Freddie Mac's PMMS or a lender directly for the latest figure before making a decision.
Most luxury purchases in Nashville sit above conforming loan limits, which means financing runs through jumbo loans rather than the conventional rates quoted in national headlines. Jumbo rates don't always move in lockstep with conforming rates and depend heavily on the individual lender, loan structure, and borrower profile — a mortgage broker who works in the jumbo space regularly is worth involving early, rather than assuming headline rates apply directly.
It's also worth remembering that a meaningful share of luxury transactions in markets like Nashville close in cash or with a large down payment, which insulates a buyer from monthly rate sensitivity but not from the broader effects rates have on market activity — fewer competing offers can mean more negotiating room, even for a buyer who isn't financing at all.
What did the Fed do to interest rates in September 2026?
On September 16, 2026, the Federal Reserve raised its federal funds rate target range by a quarter point, to 3.75%–4.00%, in a unanimous vote aimed at supporting progress toward its 2% inflation target.
What is the current average 30-year mortgage rate?
As of September 17, 2026, Freddie Mac reported the average 30-year fixed mortgage rate at 6.95%, up from 6.76% the previous week and 6.26% a year earlier. Rates change weekly, so confirm the current figure with a lender.
Should I wait to buy a luxury home until rates come down?
That's a decision that depends on your financing plan, timeline, and how much of the purchase you're financing versus paying in cash — it's worth working through with your lender and agent rather than timing the market on rate predictions alone. This isn't financial advice; a licensed lender or financial advisor can walk through your specific numbers.
Do rate changes affect cash buyers?
Not directly on financing cost, but rate-driven shifts in buyer competition can still affect pricing and negotiating leverage, which matters even to an all-cash buyer.
How is a jumbo loan different from a conventional mortgage in a rate environment like this?
Jumbo loans exceed conforming loan limits and are priced by individual lenders based on their own risk assessment, so jumbo rates can run higher or lower than conforming rates depending on the lender and the borrower's profile — shopping multiple lenders matters more than usual.
Why work with a specialist during a rate-moving market?
An agent who tracks financing conditions alongside the local luxury market can help you weigh timing, connect you with lenders experienced in jumbo and luxury financing, and put a rate move like this one in context rather than in isolation.
The Fed's September 16 rate increase and the resulting move in mortgage rates are real, dated facts — not a signal about what happens next. For Nashville's luxury buyers, the more useful question is usually how a purchase fits your own financing plan and timeline, not whether to guess at the Fed's next move.
If you want to talk through how current rates affect a specific purchase or listing, Morrell Property Collective can connect you with lenders who work in Nashville's luxury market and help you think through the timing. Call our team at (615) 593-3103.
Real Estate Market
What the September rate increase and today's mortgage rates mean for luxury buyers
Neighborhood
Where the season actually shows up in Middle Tennessee
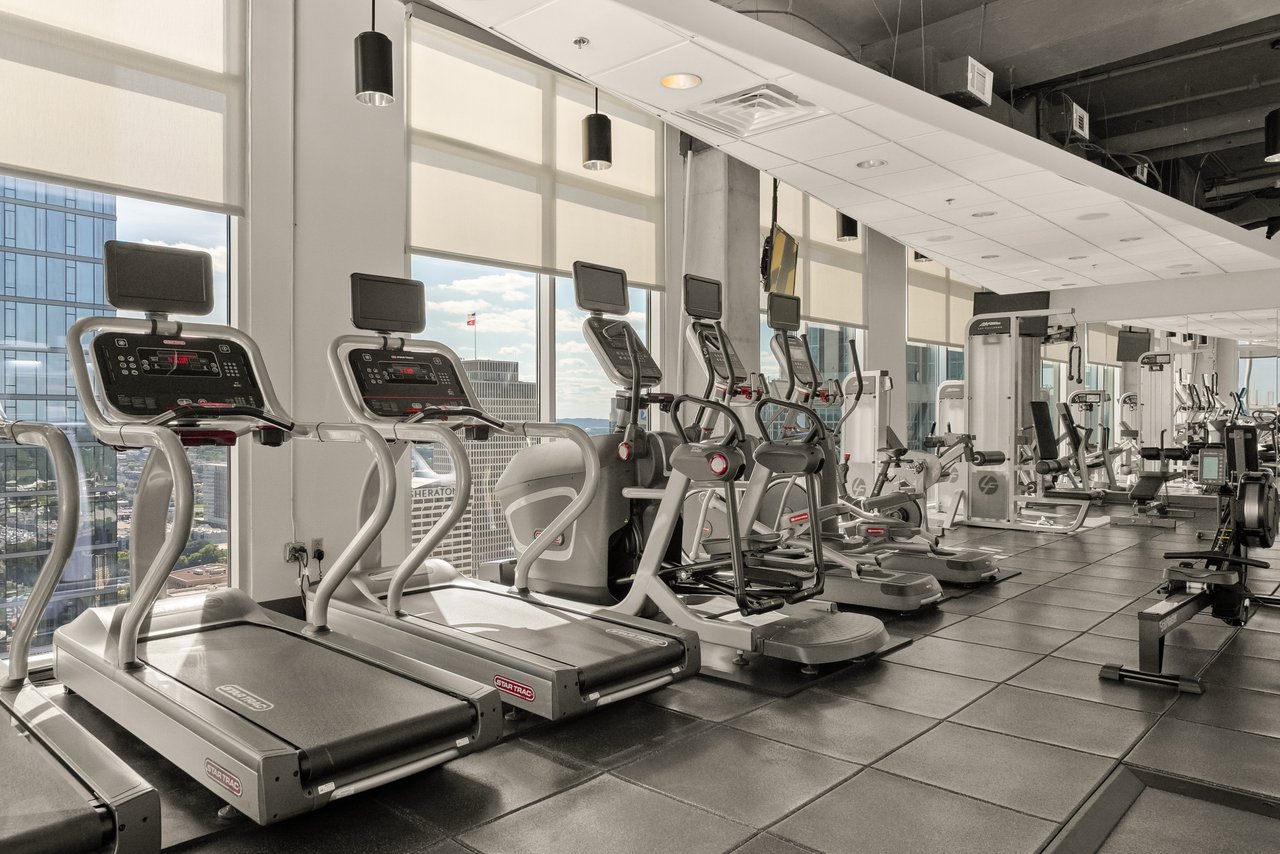
Featured Listing
A room-by-room look at life above downtown Nashville
Real Estate Market
Concierge service, skyline views, and two decades as a downtown fixture
Featured Listing
Low-maintenance, amenity-rich living just south of downtown
Featured Listing
A countryside estate defined by land, privacy, and views — not square footage
Buyers
Why it matters even more when the stakes — and the systems — are bigger
Buyers
The real data on which rooms and details shape a buyer's first impression — and why it matters more in a market where nearly half of listings don't sell.
Neighborhood
What to know about the tree-lined streets, 1920s architecture, and real price range behind one of West End's quietest luxury addresses.
The client deserves the full service and attention that only a team of experts can consistently provide. Working with us, you will have the personal attention traditionally associated with the client-agent relationship improved by the professionalism and consistency of a thoughtful business model. And yes, superior results will follow!
MORRELL PROPERTY COLLECTIVE
(615) 593-3103
[email protected]
ADDRESS
3990 Hillsboro Pike, #320
Nashville, TN 37215