Jumbo Mortgage Rates in Tennessee: What Luxury Buyers Should Know This Month
Morrell Property Collective November 9, 2026
Buyers
Morrell Property Collective November 9, 2026
Buyers
If you're buying a luxury home in Middle or East Tennessee, there's a good chance your mortgage will be a jumbo loan. That makes jumbo rates, not just the headline 30-year rate, the number to watch.
In early November 2026, jumbo rates sat in the low-to-mid 7% range nationally. That's higher than a year ago, but rates have eased for several weeks in a row. Here's what that means for your budget, and how the loan limits differ between Nashville and Knoxville.
Key takeaways
Several national sources show a similar picture for the first week of November 2026:
These are national averages. Your actual rate depends on your credit, down payment, loan size, assets, and lender.
In 2026, the conforming loan limit for a one-unit home in the Nashville metro, including Davidson and Williamson counties, is $1,029,250. Any loan above that amount is a jumbo loan. In most other U.S. counties, including Knox County, the limit is the $832,750 baseline set by the Federal Housing Finance Agency (FHFA).
This difference matters. A Nashville-area buyer can borrow nearly $200,000 more than a Knoxville buyer before crossing into jumbo territory.
Here's a simple example of principal and interest on a 30-year fixed loan:
Loan amount | Rate | Monthly principal and interest |
|---|---|---|
$1,200,000 | 6.35% (jumbo average, Nov. 2025) | about $7,467 |
$1,200,000 | 7.40% (jumbo average, Nov. 2026) | about $8,309 |
That's a difference of roughly $840 per month, or about $10,000 per year, before taxes and insurance. For many luxury buyers, it's not a deal-breaker, but it does shape how much to put down and which loan structure makes sense.
Yes, slightly. In early November 2026, the national jumbo average (about 7.35%–7.40%) ran a little above the Freddie Mac conforming average of 7.18%. The gap changes over time, and some lenders, especially private banks, price jumbo loans more aggressively for clients with large deposits or investment accounts.
Some buyers put down more than 20% to keep their loan near or below the conforming limit. In Nashville, a $1.3 million purchase with about 21% down keeps the loan near $1,029,250.
Many private banks offer rate discounts when you move assets to them. If you have significant savings or investments, ask lenders about relationship pricing.
Some buyers who plan to sell or refinance within 7–10 years compare 7/1 or 10/1 ARMs with 30-year fixed loans. ARMs carry rate risk later, so compare carefully with your lender.
On new construction, some sellers offer rate buydowns. For example, one of our Thompson's Station listings, 5007 Gates Mill Ridge, lists a seller option of a 2-1 temporary rate buydown with an acceptable offer.
How much do I need to put down on a jumbo loan?
Many lenders look for 10% to 20% down on jumbo loans, plus reserves of several months of payments. Requirements vary by lender, loan size, and your financial profile.
Is it better to pay cash for a luxury home?
It depends on your goals. Cash can make your offer stronger and avoids interest, but it ties up liquidity. Some buyers pay cash, then take out a mortgage after closing. Talk with your financial advisor and lender.
Will jumbo rates go down?
No one can predict rates with certainty. Rates have eased for several weeks in a row as of early November 2026, but they remain higher than a year ago. Focus on a payment you're comfortable with today.
Are jumbo loan limits the same everywhere in Tennessee?
No. The Nashville metro has a higher 2026 limit ($1,029,250) than most of the state, including Knox County ($832,750). Your lender can confirm the limit for your county.
Jumbo rates are higher than a year ago, but they've been easing, and smart planning can soften their impact. Knowing your county's loan limit, shopping lenders, and choosing the right loan structure can make a real difference in your monthly payment.
Morrell Property Collective works with trusted jumbo lenders across Nashville and Knoxville and can help you compare options before you shop. Call (615) 593-3103 to talk through your budget and timing.
Neighborhood
Room to breathe, new custom homes on an acre or more, and Williamson County schools, just south of Franklin.
Buyers
Where jumbo rates stand in November 2026, when your loan becomes "jumbo" in Nashville and Knoxville, and how to plan your purchase around today's numbers.
Neighborhood
Privacy, land, and quick access to Music Row: here's why artists and industry insiders gravitate to these Middle Tennessee communities.
Buyers
What New Yorkers should know about taxes, neighborhoods, and buying a luxury home in Music City.
Neighborhood
Big wooded lots, a deep connection to nature, and quick access to Belle Meade and Green Hills: here’s what to know about one of Nashville’s most private west-side neig… Read more
Nashville
From Michelin-starred tasting menus to songwriter nights and a staycation downtown, here’s how to plan a memorable evening without leaving Music City.
Featured Listing
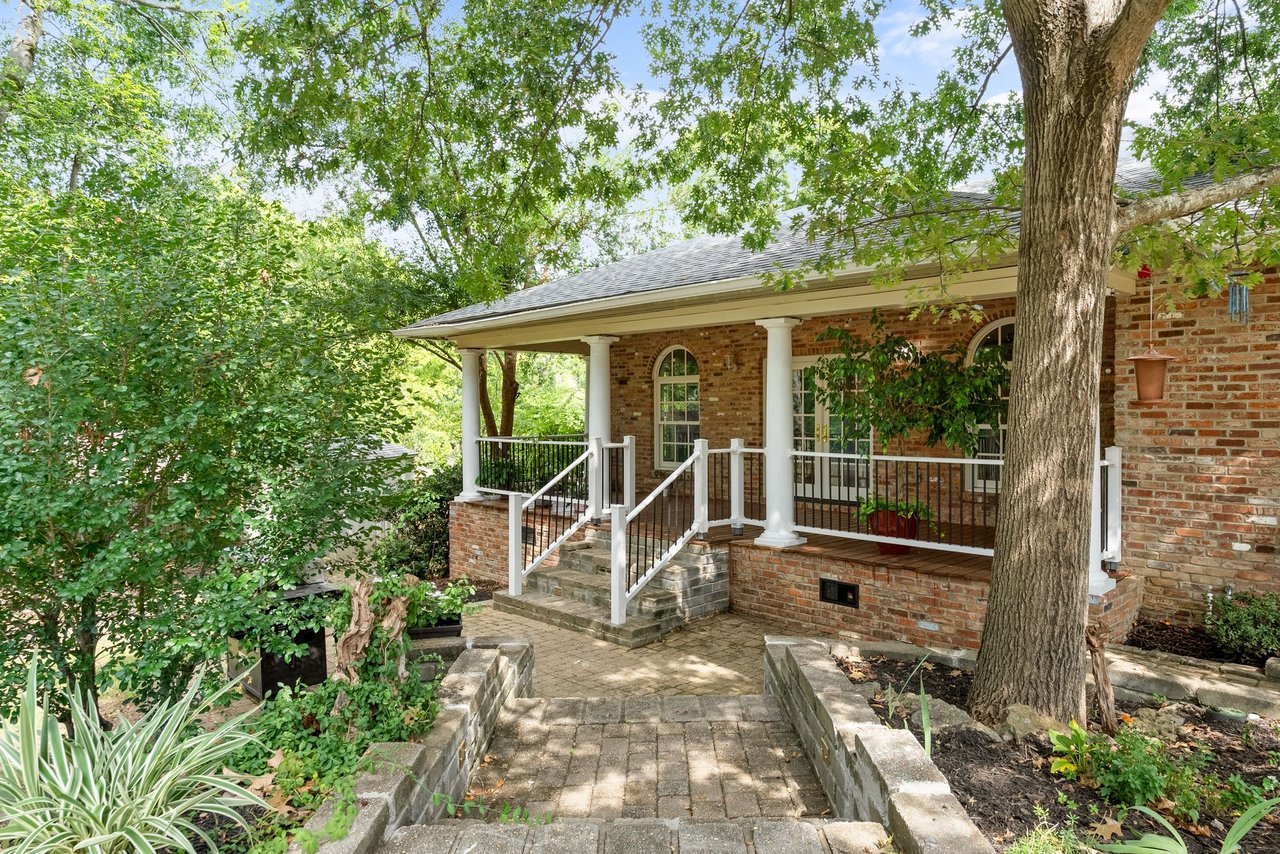
A one-level home on 1.26 acres with a pool, sauna, and workshop, minutes from Belle Meade, Green Hills, and the Warner Parks.
Franklin
The right agent can shape your price, your timeline, and your peace of mind. Here’s how to compare your options before you sign.
Neighborhood
Golf communities, lake access, strong schools, and no city property tax. Here’s what to know before you buy in West Knoxville’s most sought-after suburb.
The client deserves the full service and attention that only a team of experts can consistently provide. Working with us, you will have the personal attention traditionally associated with the client-agent relationship improved by the professionalism and consistency of a thoughtful business model. And yes, superior results will follow!
MORRELL PROPERTY COLLECTIVE
(615) 593-3103
[email protected]
ADDRESS
3990 Hillsboro Pike, #320
Nashville, TN 37215